
Profit vs Cash Flow: Why Growth Eats Your Cash
25 September 2024 · Updated 17 November 2026 · 7 min read
اقرأ المقال بالعربية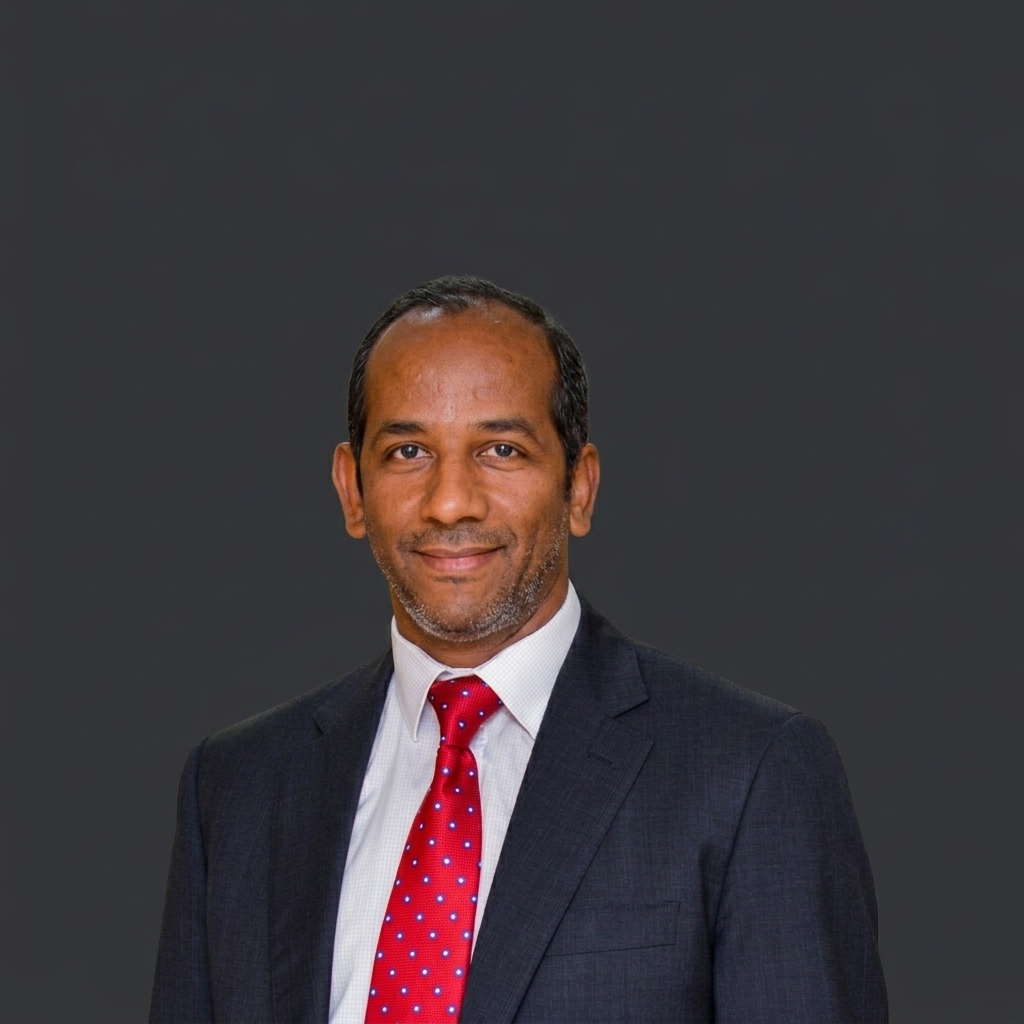
Hazem Kassem
Reviewed by Hazem Kassem — Founder & Managing Director, CMA, ACCA Certificate in IFRS Read bio →
The best sales year in your company's history can be the year you run out of cash. Orders are up, the income statement shows record profit, and yet every month ends with a call to the bank. The owner asks the same question each time: if we are making money, where is it?
The answer sits in the gap between profit vs cash flow. My view after 25 years as a CFO: growth is not free. Every extra unit of sales has to be funded before it is collected, and a company that grows faster than its own cash generation can support will run short of cash even while it is profitable. The good news is that you can calculate in advance how fast your business can grow on its own money, and which levers raise that limit.
Profit vs cash flow: why growth eats your money
Profit is recorded when you deliver and invoice. Cash arrives when the customer pays. In between, you have bought stock, paid staff and often paid suppliers. That money sits in your working capital: receivables, inventory, less what suppliers are financing for you.
For a stable business this is a one-time investment. For a growing business it is a permanent drain, because every increase in sales requires a matching increase in receivables and stock. The faster you grow, the more cash goes into the balance sheet before it can come back as collections.
Neil Churchill and John Mullins described this in the Harvard Business Review as the self-financeable growth rate: the rate at which a company can grow using only the cash its own operations generate. It depends on three things: how long cash is tied up in the operating cycle, how much cash each unit of sales requires, and how much cash each unit of sales generates. A profitable company that tries to grow faster than this rate can run out of cash even when its products sell well (Harvard Business Review).
Worked example: how much cash each extra sale needs
Example (illustrative, assumptions stated): a distributor with annual revenue of 40 million (in any currency). Cost of sales is 70% of revenue. Customers pay in 60 days, stock is held for 75 days and suppliers are paid in 45 days. Profit plus depreciation, the cash the business generates before working capital, is 7% of revenue. The company spends 1.5 million a year on equipment and vehicles. This is a simplified one-year view, before new borrowing.
Step 1: working capital per unit of sales. Receivables take 60 days of revenue. Inventory takes 75 days of cost of sales and supplier credit gives back 45 days, both at 70% of revenue. So working capital is (60 + 0.7 × 75 − 0.7 × 45) ÷ 365 = 81 ÷ 365, or 22.19% of annual revenue: about 8.88 million today.
Step 2: what growth does to cash. Each extra 1 of annual sales needs about 0.22 of new working capital, but generates only 0.07 of cash in the year.
| Growth this year | Extra revenue | Extra working capital needed | Cash generated (7% of revenue) | Cash left after working capital and equipment |
|---|---|---|---|---|
| 0% | 0 | 0 | 2,800,000 | 1,300,000 |
| 10% | 4,000,000 | 887,671 | 3,080,000 | 692,329 |
| 30% | 12,000,000 | 2,663,014 | 3,640,000 | (523,014) |
| 50% | 20,000,000 | 4,438,356 | 4,200,000 | (1,738,356) |
At 30% growth the company earns more profit than ever and still ends the year about 0.52 million short. At 50% growth it is 1.74 million short. Nothing is wrong with the business. It is simply growing faster than it can fund.
Step 3: the self-funded growth limit. Solving for the growth rate at which cash generated exactly covers new working capital and equipment gives about 21.4% for this company. Above that, growth has to be financed by the bank, by shareholders or by changing how the business runs.
Three levers that raise your growth limit
| Change | Working capital as % of revenue | Self-funded growth limit |
|---|---|---|
| Today (60 / 75 / 45 days) | 22.19% | 21.4% |
| Collect 15 days faster (45 days) | 18.08% | 29.3% |
| Also cut stock to 60 days | 15.21% | 39.6% |
- Collect faster. Fifteen days off collection time takes the limit from 21.4% to 29.3% in this example. Invoice on delivery, chase from day one, and stop extending terms by default to win orders.
- Hold less stock. Cutting inventory from 75 to 60 days lifts the limit to 39.6%. Slow-moving items are cash on a shelf.
- Improve margin. Churchill and Mullins show that a small rise in net margin has a large effect on self-funded growth, because more cash is generated on every unit sold. Price increases and cost discipline both count.
Paying suppliers later also helps, but negotiate it openly. Stretching suppliers without agreement damages the supply chain you need to grow.
A 7-point cash check before you push for growth
- Calculate working capital as a percentage of revenue from your latest balance sheet.
- Calculate the cash your business generates before working capital: profit plus depreciation.
- Work out your self-funded growth limit, including planned equipment spending.
- Compare it with this year's sales target. If the target is higher, decide now how the gap will be funded.
- Check whether growth is coming from customers who pay slower than your average.
- Build a 13-week cash flow forecast and update it every week while growth is fast.
- Agree facilities with your bank before you need them, not when the account is already overdrawn.
Common mistakes
- Judging growth on the income statement alone. The cash cost of growth appears on the balance sheet.
- Funding working capital with short-term overdrafts that are renewed in a panic. Permanent working capital needs stable funding.
- Offering longer payment terms to win new customers without calculating the cash they absorb.
- Buying stock ahead of growth that has not been confirmed by orders.
- Assuming profit will fix the cash problem. At high growth, more profit can mean more cash absorbed, not less.
Frequently asked questions
What is the difference between profit and cash flow?
Profit measures revenue earned minus costs incurred in a period, whether or not cash has moved. Cash flow measures money actually received and paid. The difference comes mainly from changes in receivables, inventory and payables, from equipment purchases and from loan repayments, none of which appear as expenses on the income statement in the same way.
Why does a growing company run out of cash?
Each increase in sales needs more receivables and stock before customers pay. If the cash generated from each sale is smaller than the working capital that sale requires, faster growth absorbs more cash than the business produces. The company can be profitable and still need funding to keep growing.
How do I calculate how fast my business can grow without new funding?
Express working capital as a percentage of revenue, calculate cash generated as a percentage of revenue, and deduct planned equipment spending. The growth rate at which cash generated equals the extra working capital and equipment needed is your self-funded growth limit. The calculation is an estimate and should be refreshed as terms and margins change.
What is the fastest way to release cash in a growing business?
Usually collections. Reducing the average time customers take to pay releases cash immediately and raises the growth rate the business can fund itself. Reducing slow-moving stock is often second. Both are faster and cheaper than new borrowing, though many growing companies need some of each.
Where to start
Take last year's revenue, receivables, inventory and payables, and calculate working capital as a percentage of revenue. Then compare your self-funded growth limit with next year's sales target. If the target is higher, the conversation with your bank or shareholders should start now. For more on reading the numbers behind this, see how to read financial statements as an owner.
If you want a senior finance professional to build your cash plan for growth, book a free 30-minute consultation with Axcell Financial Consulting, or see how a fractional CFO can manage it with you.
Sources
- Neil C. Churchill and John W. Mullins, How Fast Can Your Company Afford to Grow?, Harvard Business Review, May 2001 (accessed 17 November 2026).
The worked example is illustrative, with its assumptions stated in the text; all figures are calculated from those assumptions using a simplified one-year method. The cash check is Axcell's recommended approach.
Want to put this into practice?
Take our free 5-minute Financial Health Check — 16 questions across cash, planning, compliance and strategy. You'll get a personalised score and the recommended next step for your business.
From the CFO's Desk
One useful finance letter a month
Plain, practical notes from Hazem Kassem for business owners: one insight, one number to check, one rule or market update, and one free tool. No spam. Unsubscribe any time.
By subscribing you agree to receive these emails. We never share your details.